

The Retail market in Reno has continued to see its overall construction activity contract in Q3.
Kidder Mathews recently released its Q3 Reno Retail report. Highlights from the report include flat vacancies, lower unemployment and construction deliveries, and elevated rental rates. NVBEX has covered several of Kidder Mathews’ regional market reports.
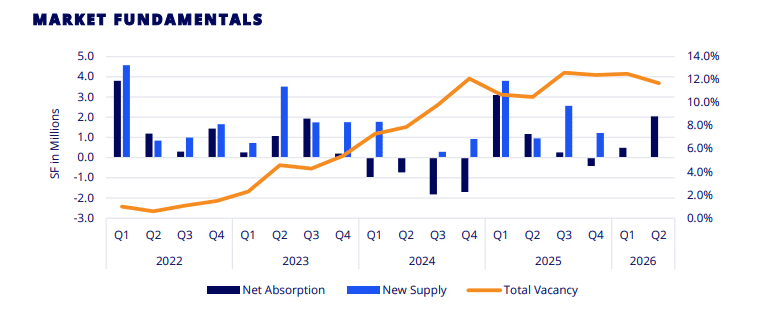
Vacancy rates remained flat quarter-over-quarter at 3.8%. This, however, reflects a 30-basis-point decrease year-over-year, as Q3 2025 had a vacancy rate of 4.1%.
The average asking rent rose significantly YoY from $1.50/SF to $1.63/SF, which is 8.9% higher. The Q2 2026 average asking rent was $1.58/SF.
The amount of space under construction continued to decline. One year ago, there was 72.9KSF under construction. The previous quarter had 61.9KSF under construction, while this quarter only had 59.5KSF. This reflects a YoY decline of 18.42%.
The average cap rate grew QoQ but declined YoY. In Q3 2026, the average cap rate was 6.3%. The previous quarter had a cap rate of 6.1%. One year ago, the cap rate was 7.3%. This reflects a decline of 100 basis points.
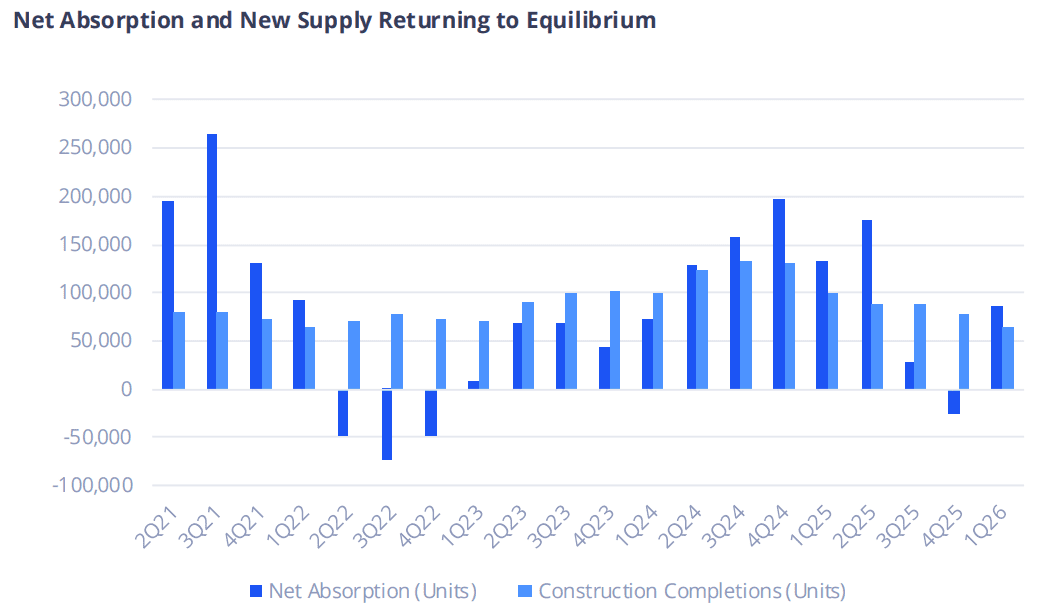
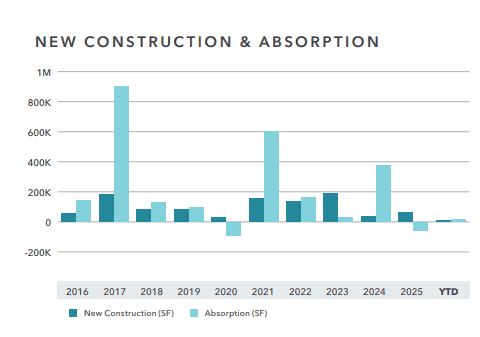
Deliveries have plummeted YoY, with the current year-to-date amount sitting at 9.4KSF. For reference, by the end of Q3 2025, 51.7KSF had been delivered. YoY, deliveries fell 81.86%. This quarter saw the delivery of 2.5KSF.
Net absorption was negative in Q3 2026 at -929SF. Year-to-date absorption is 18.1KSF. By Q3 2025, the year-to-date absorption was -146.7KSF.
The average sales price increased to $261/SF, which is significantly higher both QoQ and YoY. The previous quarter had an average sales price of $185/SF, while Q3 2025 had an average sales price of $193/SF, reflecting a 35.34% change.
The full report is available here.